
Q1 2021 Market Update

In Speculative Markets; Investing with a Margin of Safety
One permabear author and investor that I frequently read points out that the S&P 500 Price to Sales (P/S) ratio is currently around 3.1X. To put that multiple into perspective, prior to the financial crisis at the market tops in 2006/2007 the Price/Sales ratio was around 1.5X to 1.6X. At the market top in 2000 it was still well below 2X. I believe some of that increase can be explained by a larger percentage of technology and SAAS type companies having high P/S valuations and making up a larger percentage of the index. However, that change in market makeup definitely doesn’t come close to accounting for today’s excessive market valuation.
It’s difficult to liquidate shares that are up 100, 200, or 300% from where we bought them a year ago. Every market hiccup is met with stronger buying. While we want to take advantage of rage buying due to a few extra trillion dollars in bank accounts, there comes a time while the music is still playing strong to become more cautious.
Major stock market drops are not totally contingent on impending recessions. While we do not see any cause for a recession any time soon, we are concerned about sudden market corrections.
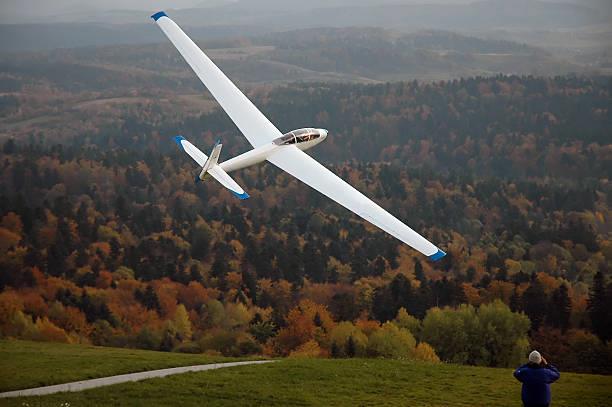
A few years ago (more than I like to remember) I took several glider flying lessons in the Tetons. Once the glider was towed to height and released, the student did most of the flying. The instructor sat in the back guiding the search for thermals. Once in a thermal the glider was guided in a tight turn higher. A few thousand feet of elevation can be gained quite quickly taking the glider up to cruising height over the Tetons. These thermals exist in odd unpredictable places, hot air rising faster than the surrounding air temperature. The opposite also exists – termed air pockets. When the glider hits an air pocket, it drops quickly. You’ve felt it before on commercial flights.
In order for the glider to escape the drop, the pilot must push the stick forward to gain air speed to escape the air pocket. As you might imagine, air pockets can be very dangerous for a glider plane, especially when over the mountains.
The market drops in October of 1987 and 1998 are examples of how the market can hit an air pocket without the expectation of a recession. Those panic style crashes were caused only by excessive valuations and record high margin debt like we have today. The U.S. market is getting unfun for value managers like us. Our price targets for the U.S. stocks we own are being run down by a stampede of not-so-brilliant retail money (did you notice how I didn’t say something that might be construed as politically incorrect like “dumb money”). We always demand some kind of margin of safety, reasonable valuation by one metric or another for the equities we own. It could be earnings multiples, free cash flow multiple, book value multiple, cash on the balance sheet, distributable cash flow, Price/Sales ratio, EV/EBITDA. Something! There must be a calculation from which to derive an intrinsic valuation. Those attractive investments we have been able to find recently have hairy issues that make many types of investors uncomfortable.
A Few Stocks we Like
Below are a few examples. Do not read this and go buy these stocks. They all have something gnarly, nasty or unfortunate going on and must be kept up with closely. You will not know when we sell them.
EBIX – This online insurance exchange business is recently in the sale bin after the firm’s international accounting firm fired the company. The accounting firm withdrew their services prior to the company’s 10K filing due to what they explained was a problem with the way the firm was handling information from it’s fast growing Ebix Cash business in India.
Why we like it: Trading at 8.6X earnings, with a typical growth rate ranging from 15X to 30X, and a potential IPO of the company’s Ebix Cash unit in India in Q1 2022.
Alibaba – The Chinese government recently fined the company $2.4B for antitrust violations. Q1 earnings were hurt some from the actions taken to come back into compliance. There is also regular speculation and mystery surrounding Jack Ma, the famous founder of the company, and his strained relationship with the government.
Why we like it: A+ Balance Sheet. Wide moat business with 40% organic revenue growth, excellent operational execution, and a forward P/E of less than 20X. The cloud business segment will become profitable soon.
Viatris – Created from a large merger in late 2020, this global pharma company has expiring drug patents on pharmaceuticals such as Viagra, Lipitor, and Epi Pen. Questions prevail about how cost savings and new growth areas will keep the company from shrinking.
Why we like it: Potential $3.75 in earnings per share in a year or two, means today’s $16 price tag, yields around 23% in earnings. 10X that $37.50 would more than double the share price. They will pay a nice dividend in a yield-starved environment.
Inflation Considerations
Most economists are comfortable with the Fed’s prediction that inflation will not become a problem mid to long term and will quickly dissipate. We are not so confident. Recent market jitters have been a direct result of those fears. All the ingredients for inflation seem to be in place. Supply shortage, demand increase, money supply growth, and most importantly fiscal stimulus deposits sitting available in bank deposit accounts. Once inflation gets going it may be more difficult to squeeze it back into the genie bottle than is currently believed.
In April the all-index year over year price change in the CPI was 4.2%. That’s a big number when you consider the Fed’s stated goal of 2%. After looking through the report, there were some staggering changes. For example, used trucks and cars increased in price by over 20%. Rental cars were up 82% in price.
The reason stock prices decrease due to inflation pressures is not due to inflation itself. It’s due to the potential increase in interest rates, earlier than later as a result of the underlying inflation pressure.
Look out below! I invite you to go back a year, and read the Q1/2020 Fortunato market update (the link below). The difference in sentiment and market conditions is striking!
https://www.fortunatofunds.com/newsletters/Fortunato%20Q1%202020%20Newsletter%202%20PDF.pdf
All investments involve risk, including the possible loss of principal.
The comments, opinions and analyses expressed herein are for informational purposes only and should not be considered individual investment advice or recommendations to invest in any security or to adopt any investment strategy. The opinions and analysis are rendered as of publications date and may change without notice. The information provided in this material is not intended as a complete analysis of every material fact regarding any security, country, region, or market.
