
Q4 2021 Market Update

Large Potholes Not Minefields
Even though the market ended 2021 with a Santa Clause rally, the last few months were full of churn, stock and sector rotation into and out of and into again the same issues and industries. It was an extremely difficult period as around 80% of stocks experienced at least a 10% pullback at varying times. The difficulty was masked by the index averages, propped up by a few mega cap stocks.
Going forward, there are a few themes to guide investments with regard to rising interest rates, inflation and playing some defense. I believe we will have increased volatility in the form of 8 to 12% market corrections rather than the 3 to 4% pullbacks in 2021. This was my thought heading into the year when we raised cash at the end of 2021. We’ve already had one nearly 10% correction. As of this writing the S&P 500 sits at around 5% below itspeak.
When you’re defending the jump shot, don’t leave your feet until the last 1000th of a second, lest your opponent fake the shot, and blow by you to the rim. That is, don’t take the bait on a small dip in a richly valued stock nor on a quick pullback. Time and patience during these first 6 months of 2022 should yield some good opportunities. After all what’s the rush? The market still sits near the most expensive levels ever, with an S&P 500 yield of just 1.3% and a Price/Sales ratio of 3X. As we have just seen with 25% declines in a day for Paypal and Facebook (Meta) shares, it can get severe quickly. Palantir is down nearly 50% since November.
The specter of tightening monetary policy in the form of tapering the Fed’s bond buying and raising interest rates is going to be especially painful for the most speculative securities, crypto and real estate. This past decade is the first in the last 100 years you could buy a basket of stocks trading above 10X sales and do better than the overall market. In every other prior decade, that was a formula for disaster. That will change in 2022. There is no more extraordinary stimulus on the way. In this type of environment, the market changes its attitude from “tell me a good narrative” to “demonstrate the story with figures.”
We’ve seen the incredible inflationary impacts of fiscal stimulus and a related unorganized strike by the workforce. Nearly every earnings call I listen to echoes the themes of drastically increased materials prices, supply chain problems, and labor cost increases. One company I follow (Ebix) was forced to raise the salaries of their software developers in India by 50% to fend off poachers. A mining company (Argonaut) saw the cost estimate of developing a previously scheduled gold mine in Guatemala skyrocket 70%. Let’s talk Cheerios. General Mills missed earnings and the stock dove 4% on soaring raw materials and freight and labor costs. These conditions are unrelenting. Companies are having a difficult time finding the people theyneed.
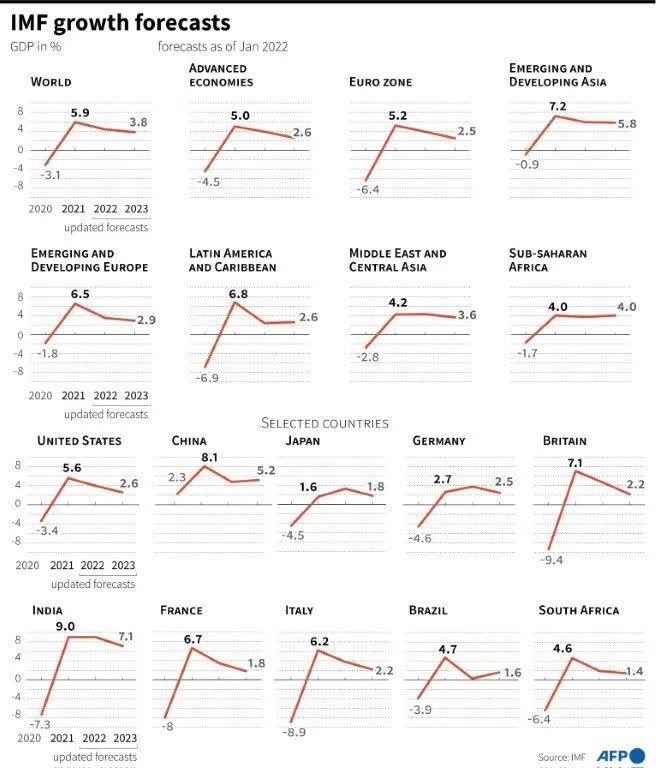
So where does the year go from here? A few large potholes in the first half maybe through the summer, but avoid a recession (minefield) would be my guess. I think we will end up flat or slightly positive for the year. Inflation will come down, but remain elevated in the 3 to 3.5% range while economic growth slows to trend. The IMF prediction has U.S. economic growth slowing to 2.6% by mid 2023.
Below are IMF economic forecasts for the world and large economies:
So far during this more volatile year, despite holding heavy cash equivalents, we’re cautiously energized about some of the opportunities opening up. Despite the head winds, good companies find ways to overcome challenges and increase earnings. Analyst estimates for S&P earnings growth in 2022 are 9%. Whatever happens we will be disciplined in our approach to finding value and remember the following:
“The stock market is a device for transferring wealth from the impatient to the patient.” -WB
We wish you peaceful, safe, enjoyable Covid free spring.
=S Dee
All investments involve risk, including the possible loss of principal.
The comments, opinions and analyses expressed herein are for informational purposes only and should not be considered individual investment advice or recommendations to invest in any security or to adopt any investment strategy. The opinions and analysis are rendered as of publications date and may change without notice. The information provided in this material is not intended as a complete analysis of every material fact regarding any security, country, region, or market.
